This Week
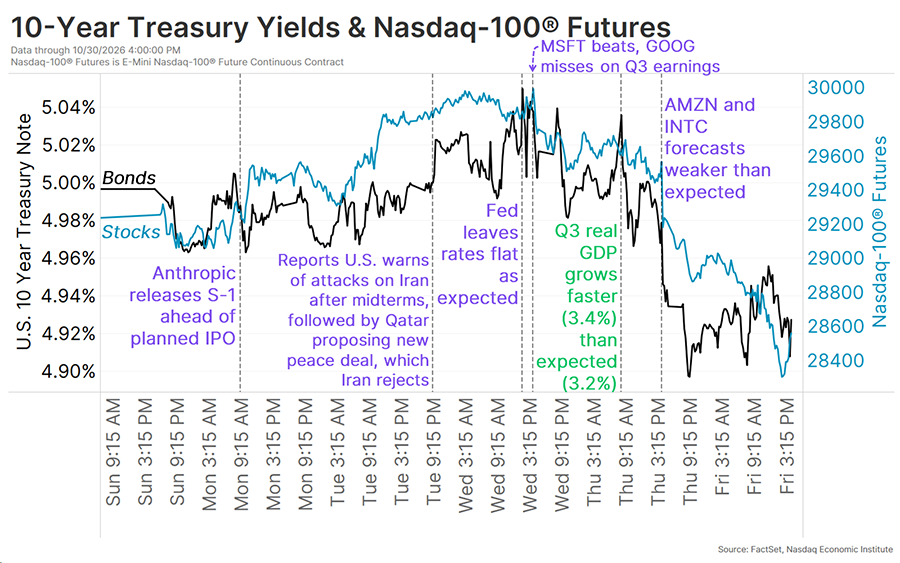
The artificial intelligence (AI) trade was the top theme for markets this week, but the Federal Reserve, major economic data and continued developments in the Iran conflict also mattered.
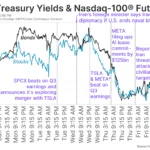
The news on the AI trade was decidedly mixed:
Still, the Nasdaq-100® is on pace for 49% YOY Q3 earnings growth.
But it wasn’t all AI this week:
- The Fed left rates unchanged as expected, though markets see a 75% chance of a December hike.
- Data showed a strong economy and still-high inflation, with Q3 real GDP growing at a 3.4% annual pace, led by strong consumer spending and AI capex (though imports were a drag since most AI data center components are imported), while headline PCE inflation rose to 3.6% YOY (as expected) from 3.4% – largely due to energy inflation.
- U.S. oil prices are up a dollar per barrel and remain above $100, even with Qatar and Vice President Vance making efforts at diplomacy, amid talks of renewed attacks on Iran after the midterm elections.
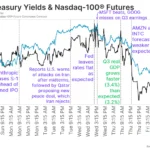
So, as has been the trend the last couple of weeks, 10-year Treasury yields are down over 5 basis points to below 4.95% on apparent safe-haven demand as the selling of AI names has the Nasdaq-100® down 2% for the week.
Image

Next Week
Here are the top events I’m watching next week:
- Monday: ISM & S&P Manufacturing PMIs (October), AAPL Earnings (Q3)
- Tuesday: JOLTS Job Openings (September), AMD Earnings (Q3)
- Wednesday: ISM & S&P Services PMIs (October)
- Thursday: Productivity (Q3), Jobless Claims (week ending Oct. 24)
- Friday: Nonfarm Jobs (October)
5 Stocks Our Experts Predict Could Double In the Next Year
By submitting your email, you'll also get a free pivot & flow membership. A free daily market overview. You can unsubscribe at any time.