The Tech Sector’s Meteoric Rise
In recent years, the technology sector has been a golden goose for investors. Fueled by the artificial intelligence (AI) megatrend, tech stocks have delivered mesmerizing rallies that have propelled the overall markets to dizzying heights. The surge of the “Magnificent Seven” stocks alone added a mind-boggling $5.1 trillion in total market cap in 2023, demonstrating the sector’s dominance.
The Pitfalls of Overvaluation
Despite the success stories, not all tech stocks are created equal. The fervor surrounding AI has led to pockets of overvaluation, where short-term price gains have outpaced underlying fundamentals. This scenario poses a cautionary tale for investors, especially those eyeing entry into the red-hot tech sector.
The Case Against Pure Storage
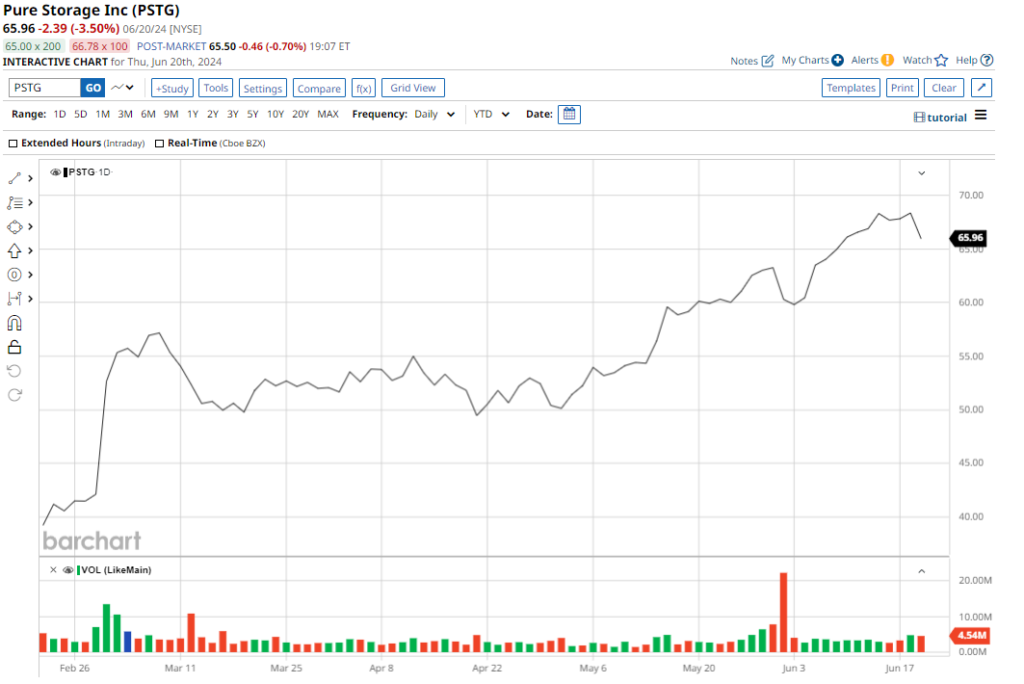
One such stock that has garnered attention is Pure Storage (PSTG), known for its innovative storage solutions. While the company enjoyed an impressive 80.8% YTD surge in 2024, concerns loom over its valuation metrics. With forward earnings trading at 41x and sales at 6.85x, the stock appears pricey, signaling a potential disconnect between price and value.
Competition and Headwinds
Pure Storage faces stiff competition from tech giants like Google, Amazon, and Microsoft in the all-flash storage arena. The influx of new players could squeeze profit margins and challenge Pure Storage’s market positioning. To weather the storm, the company must fortify its competitive edge and brand identity to stay ahead in the race.
The Analyst’s Verdict
Morgan Stanley’s recent downgrade of Pure Storage to “Equal-weight” underscores these concerns. While a cloud deal might boost revenue in the future, immediate catalysts for growth are limited. Analysts maintain a “Moderate Buy” rating for PSTG, with a mean target price slightly above its current value.
Corning’s Long Legacy and Shortcomings
Established in 1851, Corning (GLW) boasts a rich history of innovation in materials science. However, despite its diverse business segments and solid YTD performance, the company faces challenges. Declining core sales in Q1 and a dwindling cash balance relative to debt levels paint a mixed picture of Corning’s financial health.
Opportunities Amidst Uncertainty
Amidst these hurdles, Corning stands to benefit from AI data center demands and emerging environmental regulations. The company’s overlooked environmental technologies division could witness growth, especially with the impending adoption of new EPA standards. These factors offer a glimmer of hope amidst the uncertainty surrounding Corning’s outlook.
Analysts’ Assessment
Morgan Stanley’s shift to “Equal-weight” for Corning reflects a balanced risk-reward proposition at current levels. Analysts maintain a “Moderate Buy” rating for GLW, with a mean target price close to its current trading value.
Unraveling Twilio’s Market Movements and Prospects
Twilio: A Modern Communication Marvel
Twilio (TWLO), a pioneering cloud communications platform established in 2008, offers software developers a range of Application Programming Interfaces (APIs) for seamless integration of voice, video, messaging, and authentication functionalities into their applications. This strategic approach enables businesses to enhance their products with communication features like SMS notifications, two-factor authentication, and video conferencing without the burden of infrastructure development. With a substantial market cap of $9.15 billion, TWLO boasts significant market presence.
Despite a challenging year-to-date performance, with TWLO stock down by 27.8%, Twilio surprised investors with its Q1 2024 results exceeding expectations.

Twilio’s Financial Triumphs and Setbacks
During the first quarter of 2024, Twilio witnessed a revenue surge of 4% compared to the previous year, reaching $1.05 billion, accompanied by a notable increase in active customer accounts from 300,000 to 313,000. Furthermore, the company’s earnings per share (EPS) skyrocketed by 70.2% to $0.80, surpassing the Street’s predictions of $0.59. Notably, Twilio has consistently outperformed consensus estimates for the past five quarters.
Despite these achievements, analysts voiced concerns over Twilio’s Q2 revenue guidance falling below estimates at $1.06 billion. Of particular worry was the potential impact of customer turnover on Twilio’s Segment business growth. Not to mention, the market was abuzz with maverick investor Cathie Wood’s significant divestment from TWLO stock over recent months.
Morgan Stanley’s downgrade of TWLO stock to “Equal-weight” from “Overweight” also spotlighted the challenges ahead, citing a lack of imminent top-line motivators within the next year. However, the long-term potential of Twilio’s AI capabilities remained a bright spot amid the uncertainties.

Future Prospects and Analyst Insights
Looking ahead, Twilio’s strategic focus on AI integration, including generative AI across its platform and the successful adoption of CustomerAI predictive analytics tools, positions the company for sustained growth. Leveraging collaborations with tech giants like Google and OpenAI further fortifies Twilio’s competitive edge, especially in serving its substantial customer base of 300,000.
With a global developer outreach of over 10 million, Twilio’s customer engagement platform solidifies its status as a Communications Platform as a Service (CPaaS) powerhouse.
Currently, analysts maintain a “Moderate Buy” rating for TWLO stock, foreseeing a mean target price of $69.08, indicating a potential upside of around 26.2% from current levels. Of the 29 analysts covering the stock, 10 have a “Strong Buy” rating, 1 holds a “Moderate Buy” rating, 16 rate it as “Hold,” while 1 each recommends “Moderate Sell” and “Strong Sell”.
5 Stocks Our Experts Predict Could Double In the Next Year
By submitting your email, you'll also get a free pivot & flow membership. A free daily market overview. You can unsubscribe at any time.